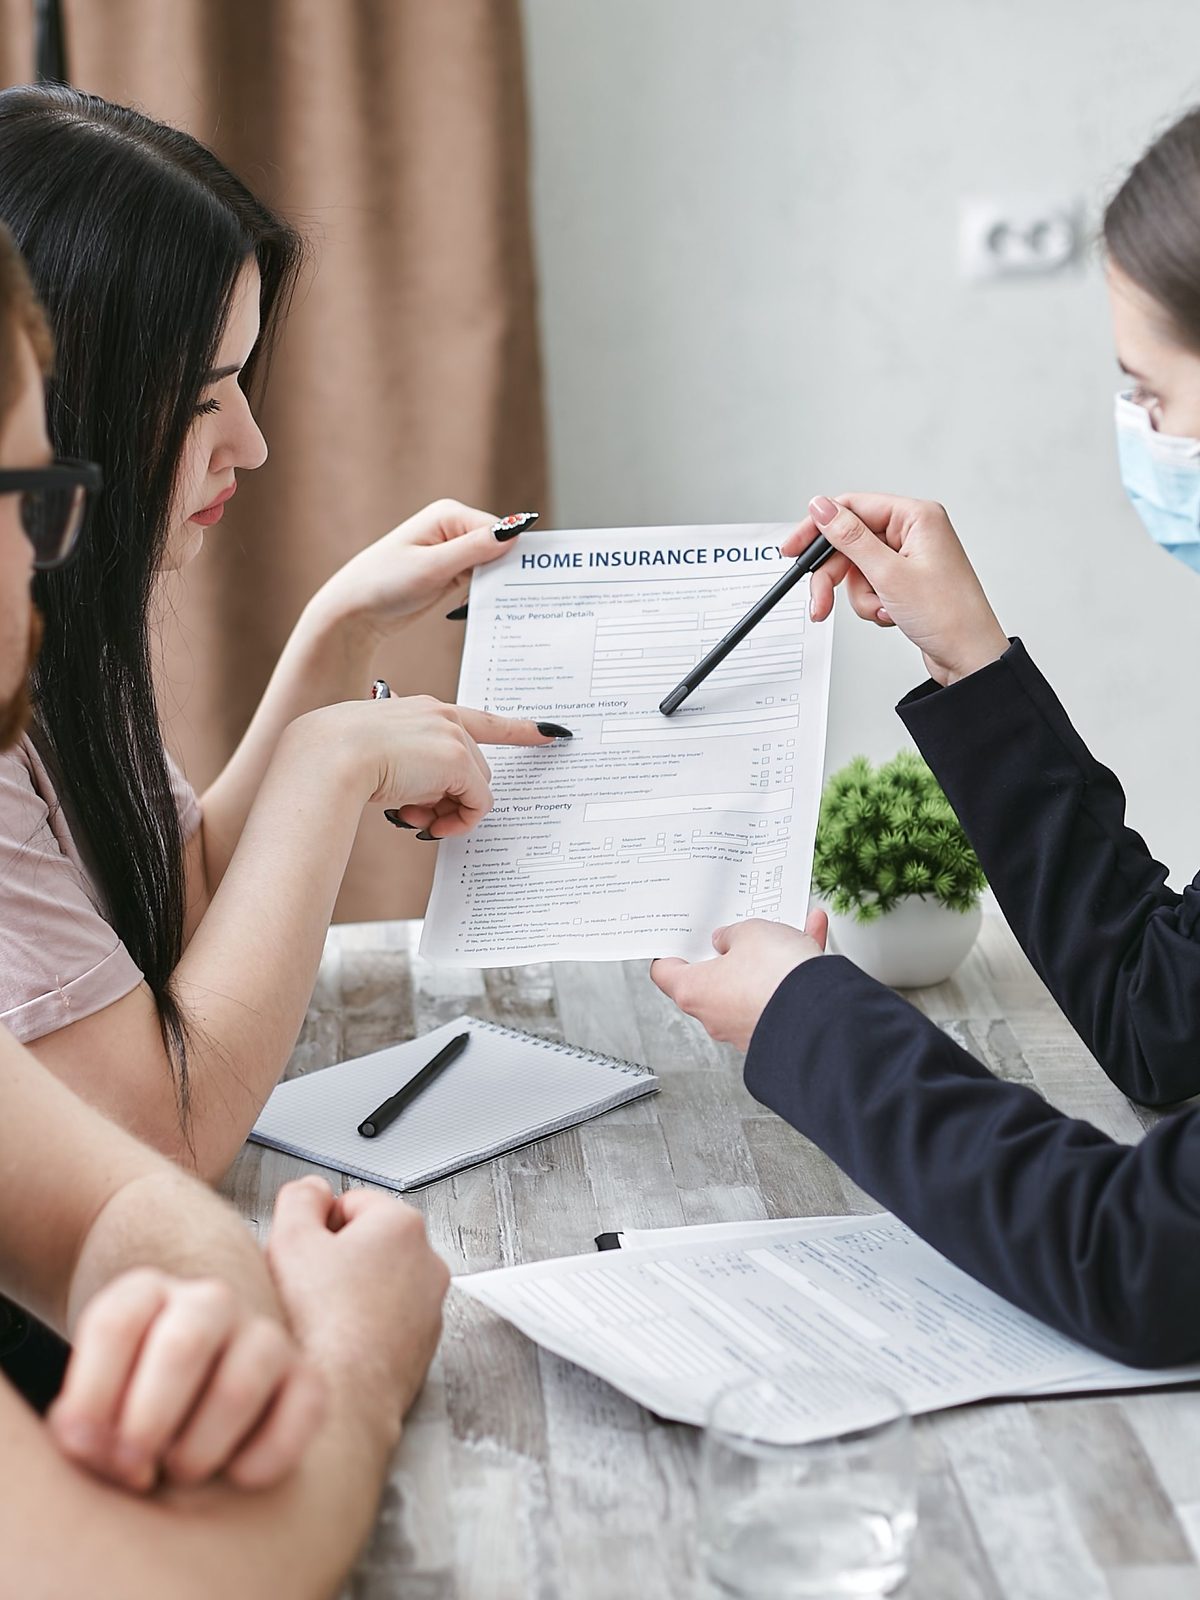
A public claims adjuster is a licensed professional hired by a policyholder to handle an insurance claim on their behalf. The title varies by state, and public adjuster, public claims adjuster and public insurance adjuster all describe the same licensed role. They are paid almost without exception as a percentage of what the insurer pays, which means you are not buying hours. You are selling a share of the outcome.
That arrangement sounds simple and conceals most of the cost. Two agreements quoting the same percentage can take very different amounts out of the same claim, depending on what the percentage is applied to, whether money already paid is included and whether anything is billed on top. The fee agreement is where the real price lives.
What the role actually covers
A public adjuster reads the policy, inspects or commissions an inspection of the loss, prepares a claim with an estimate and supporting evidence, presents it to the insurer and deals with the carrier through the file. On a roof claim that usually means arguing about scope and cause: what was damaged, by what, and what putting it back requires.
What the role does not include is legal representation. A public adjuster is not an attorney and cannot act as one, and claims that need litigation need a lawyer instead. The role also does not include doing the roofing work. Several states bar a licensed adjuster from contracting to repair the same property, for the obvious reason.
The reverse restriction matters more to owners. In many states, negotiating a claim on a policyholder’s behalf requires an adjuster license, so a roofing contractor who offers to handle the claim is offering something they may not lawfully do. Our page on public adjusters sets out where that line sits and how to check a license.
How the fee is structured
| Structure | What the percentage applies to | Where it appears |
|---|---|---|
| Gross settlement | Every dollar the insurer pays on the claim | The most common form |
| Additional recovery | Only the increase over what was already offered | Where an offer exists already |
| Contingent with a minimum | The recovery, but not below a stated floor | Smaller claims |
| Hourly or flat | Time or a fixed sum, regardless of outcome | Uncommon, usually consulting |
The first two are the ones to tell apart. If an insurer has already issued payment and the dispute is about a shortfall, a gross settlement fee charges you for money that arrived before anybody was engaged. A fee on the additional recovery charges only for the work done. Ask which applies, then ask for the answer in the contract.
Then ask what sits outside the percentage. Engineering reports, laboratory testing, estimating services and specialist inspections are sometimes billed separately, and on a complex loss they are not small.
One more term decides when you pay. Some agreements take the fee from each payment as it arrives, which means the first check is reduced before any work has been done to improve the claim. Others bill once the file closes. Neither is unusual, and the first is harder on cash flow at exactly the point you are trying to get a contractor started, so it belongs in the comparison rather than in the surprise column.
What a cap does and does not promise
Many states set a maximum percentage, and many reduce that maximum for claims arising from a declared catastrophe. A cap is a ceiling rather than a price, so a quoted figure at the cap is not a bargain and a figure below it is not a concession.
Your state insurance department publishes the rules that apply where you live, including the cap, any required contract language and any mandatory cancellation window. That is the source worth checking, and checking it is free.
The arithmetic of whether it is worth it
Three numbers decide it, and you can estimate all three before signing.
- The gap. What the insurer has offered against what the work will actually cost, priced from a measured scope rather than guessed.
- The base. Whether the fee attaches to the whole settlement or only to the increase.
- The realistic recovery. Not the best case. What a documented claim of this type plausibly recovers, which an experienced adjuster can describe from their own files without promising anything.
Apply the percentage to the base, not to the gap, and compare the result with what you expect to gain. A large gap on a stalled or complicated claim usually carries the fee comfortably. A modest gap that comes down to four missing line items generally does not, because a supplement supported by photographs and measurements can close that without paying a share of everything.
Cheaper routes to the same place
Before engaging anybody on a percentage, it is worth exhausting the evidence based options, because most shortfalls are evidentiary rather than adversarial.
- An independent inspection that documents each finding and separates storm damage from existing wear, written as a report rather than as a bid.
- A measured repair scope with quantities, which lets the insurer check the numbers instead of accepting or refusing a total.
- A supplement for each missing line item, with a photograph, a measurement or a code reference attached to it.
- A complaint to your state insurance department where the problem is how the file has been handled rather than what the policy says.
Underpaid roof claims covers the recoverable depreciation that owners most often leave unclaimed, which is frequently the whole of the apparent shortfall and needs no representation at all.
Questions to ask before you sign
- What is the percentage, and what exactly is it applied to?
- Are payments I have already received excluded, in writing?
- Is there a minimum fee, and when does it fall due?
- What do I owe if the claim is denied, or if I withdraw it?
- Who pays for engineers, estimators and laboratory work?
- How many roof claims have you handled in this state, and may I speak to two of those clients?
- What is the cancellation right, and how long does the agreement last?
An established firm answers all seven without hesitation and hands you a copy to read at home.
What we do and what we do not
We inspect roofs and document them. We produce a report that locates each finding, photographs it and distinguishes event damage from existing condition, and we can write a repair scope detailed enough for another contractor to price the same work.
We are not public adjusters and we are not attorneys. We do not file claims, negotiate with carriers or settle claims on anybody’s behalf, because that is licensed work. Where a claim needs somebody acting for you, we say so and explain how to find a professional licensed in your state.
Where to go next
If you have decided representation is the right move, how to find a licensed public adjuster covers verifying a license and the solicitation rules that apply after a storm. If the claim has been refused outright rather than underpaid, start with a denied roof claim instead, because the first step there is understanding the stated reason.
Common questions
What does a public claims adjuster charge?
A percentage of what the insurer pays, set in the contract rather than by a published rate card. Many states cap the percentage, and some cap it more tightly after a declared disaster, so the lawful maximum where you live is a matter of public record at your state insurance department.
- The fee is contingent on recovery in almost every case
- State law may cap the percentage, and the cap varies
- Caps often tighten for catastrophe claims
- A minimum fee may apply regardless of the recovery
- Reports and engineers may be billed on top
Because the figure is negotiated rather than fixed, the only reliable way to know what you are agreeing to is to read the agreement and ask what the percentage is applied to. Two contracts quoting the same percentage can cost very different amounts depending on that answer. Ask your state insurance department for the fee rules before you sign, not after, because the regulator publishes them and the person asking for your signature has an interest in the outcome.
Is the fee taken from the whole settlement or only the extra recovered?
Both arrangements exist, and the difference is large. A fee on the gross settlement applies to every dollar the insurer pays, including money already offered before you engaged anybody. A fee on the additional recovery applies only to what the adjuster actually adds.
- Gross settlement fees apply to the entire payment
- Additional recovery fees apply only to the increase
- The second is better value where an offer already exists
- Check whether payments already issued are included
- Get the definition written into the contract itself
The arithmetic decides whether engaging anybody makes sense. Where an insurer has already paid a substantial amount and the dispute is about the shortfall, a percentage of the gross can consume much of what is recovered. Where nothing has been paid and the claim is complex, a gross fee is a more ordinary arrangement. Neither is wrong, and an adjuster who will not define which one applies in writing has told you something useful about how the rest of the file will go.
Who pays the public adjuster if the claim is denied?
On a purely contingent agreement, nobody: no recovery means no percentage. The exceptions are the ones to look for in the contract, because a minimum fee, an hourly fallback or a charge for third party reports can all survive a denial.
- A contingent fee with no recovery usually means no fee
- Minimum fee clauses can apply anyway
- Engineer and estimating costs may be billed separately
- Ask what happens if you withdraw the claim
- Ask what happens if the file closes with no payment
This is worth settling before signature rather than hoping. Ask the question plainly: if this claim is denied and stays denied, what do I owe you, and for what. Then look for that answer in the contract rather than in the reply. Where specialist reports are likely to be needed, ask who commissions them, who owns them afterwards and whether you are liable for their cost in a file that recovers nothing.
Does the fee apply to money the insurer paid before I signed?
It can, which is why the question matters. Where the contract is written against the gross settlement with no carve out, payments already issued and depreciation already released can be counted in the base the percentage is calculated on, even though no work was done to obtain them.
- Ask for prior payments to be excluded in writing
- Name the amounts already received in the agreement
- Recoverable depreciation is money too, and often substantial
- Supplements already approved may also be in scope
- Keep your own record of every payment and its date
Bring the payment history to the first meeting: dates, amounts and what each payment covered. An adjuster working in good faith has no difficulty excluding what was already on the table, and the exclusion costs them nothing on a claim they expect to improve. Refusal is a signal. It also helps you compare two proposals honestly, because a lower percentage on a wider base can cost more than a higher percentage on the increase alone.
What should a public adjuster fee agreement put in writing?
The percentage, what it is applied to, the treatment of money already paid, any minimum fee, who pays for third party reports, the cancellation right and the duration of the agreement. All of it in the document you keep, not in a conversation.
- The percentage, and the base it is calculated on
- Exclusion of payments already received, if agreed
- Any minimum fee and when it falls due
- Who commissions and pays for reports
- Cancellation terms and the length of the engagement
Many states require a cancellation right to be printed in the contract, and several require specific disclosures and a filed contract form. Ask for a copy to take away and read, which is a reasonable request that an established firm expects and a door to door operator resists. Verify the license with your state insurance department first, because unlicensed operators appear in storm areas within days of a loss and a license check takes minutes. Never sign anything on the day of a first visit, however urgent the roof looks or the visitor says it is.